When geopolitical conflicts escalate, energy and defense stocks often become key investment opportunities. The ongoing Middle East tensions in March 2026 have significantly impacted markets, with Brent crude prices surging 13% in a single session and defense ETFs gaining 2.8% in one day. This article highlights 15 companies across LNG, oil, and defense sectors poised to benefit from rising commodity prices, increased military spending, and supply chain disruptions. Key takeaways:
- Energy Stocks (LNG & Oil): Companies like Cheniere Energy, Excelerate Energy, Exxon Mobil, and Chevron are thriving due to rising natural gas and crude oil prices, with Brent crude nearing $95 per barrel.
- Defense Stocks: Firms such as Lockheed Martin, Northrop Grumman, and RTX Corporation are benefiting from heightened global defense budgets, with record-breaking backlogs and increased production of key weapon systems.
- Market Trends: Airline and travel stocks have suffered losses, while U.S.-based energy producers and defense contractors gain from stable domestic operations and global demand.
Quick Market Snapshot:
- Brent crude prices surged 13% in one day, reaching $94.65.
- U.S. defense ETFs rose 2.8% in response to military escalations.
- Global travel stocks lost $22 billion due to rising fuel costs and reduced demand.
This guide explores how these companies are positioned to capitalize on the current geopolitical and market dynamics.
How Do Geopolitical Conflicts Impact Crude Oil Futures?
When military conflict gets worse, energy markets move first and ask questions later. Brent crude went past $99 per barrel as Houthi strikes on Saudi Arabian cities got more intense, while U.S. forces destroyed Iranian tankers in the same week. The market is pricing in a specific fear: that the physical infrastructure moving oil from producer to consumer is suddenly at risk.
"Brent crude surged past $99 per barrel as Houthi strikes intensified and Iranian tankers were destroyed — energy markets always react to physical infrastructure threats before any other signal."
🚨 Warning: Traders who ignore geopolitical escalation signals risk being caught off-guard by sudden price spikes — energy markets do not wait for confirmation before moving.
| Geopolitical Event | Market Impact | Key Risk |
|---|---|---|
| Houthi strikes on Saudi cities | Brent crude surged past $99/barrel | Supply disruption fear |
| U.S. forces destroying Iranian tankers | Immediate price volatility | Physical tanker route risk |
| Combined escalation in same week | Compounded market panic | Infrastructure integrity |
💡 Key Insight: The real driver behind crude oil futures spikes isn't just conflict itself — it's the market's perception that critical oil infrastructure and shipping routes are at genuine, immediate risk.
How do supply disruptions and trader expectations drive oil price spikes?
According to U.S. Bank's analysis of geopolitical conflict and global markets, oil prices rose more than 5% within days of the Russia-Ukraine conflict. Brent crude at $85 per barrel reflects both current supply constraints and trader expectations. Traders are pricing in OPEC+ cuts of 2 million barrels per day and Red Sea blockades that have increased Middle Eastern shipping costs by 12%.
Why Energy Stocks Outperform During Geopolitical Stress
When supply tightens and prices rise, revenue for integrated oil majors improves quickly. ExxonMobil climbing 22% year over year and TotalEnergies up 25% reflect a structural reality: companies with proven reserves and established production capacity become more valuable when new supply is hardest to bring online.
U.S. Bank's research on geopolitical conflict and market performance found that energy sector stocks outperformed the broader market by more than 20 percentage points during periods of elevated geopolitical risk. Conflict compresses supply while demand remains stable: heating fuel, aviation fuel, and industrial energy are essential. Inelastic demand combined with unpredictable supply rewards producers.
What OPEC+ decisions actually signal to investors?
OPEC+'s March 2026 decision to cut 2 million barrels per day demonstrated the cartel's commitment to defending a price floor above $80 per barrel. After the January 2026 cut of 1.5 million barrels successfully maintained prices during the initial Middle East escalation, the March decision confirmed a pattern: OPEC+ manages demand uncertainty by managing supply with increasing precision.
How does supply discipline create a structural floor for energy stocks?
For investors watching crude oil futures and energy sector stocks, this matters because it reduces a variable in an otherwise chaotic equation. Sanctions on Russian exports have removed roughly 12% of global supply from the market in Q1 2026. With OPEC+ enforcing production discipline, the floor under oil prices is structural. ConocoPhillips at $105 per share and Chevron at $110 trade at these levels partly because the market trusts that supply will not suddenly flood back in.
The Strait of Hormuz and the Hidden Multiplier
The Strait of Hormuz is the single most important chokepoint in global energy trade and sits at the center of U.S.-Iran tensions. Saudi Arabia has already begun rerouting crude exports to avoid it, adding cost and time to every barrel. If rerouting options become strained under continued Houthi and Iranian pressure, the market will reprice energy risk sharply upward, and $100 Brent will look less like a ceiling and more like a staging point.
Most traders tracking war-related oil price movements focus on headline events. The deeper signal lies in shipping data: Suez Canal disruptions already affect 10% of global shipping and will compound as the conflict continues. Monitor freight rates, tanker availability, and regional refining capacity—these secondary indicators often move before headline prices and signal where the next pressure point is forming. Futures traders acting on those signals in CL and NG typically execute from a CME VPS in Chicago, where headline-driven spikes are measured in milliseconds.
The real question for your portfolio is which specific positions offer the most exposure to price upside with the least vulnerability to sudden diplomatic resolution.
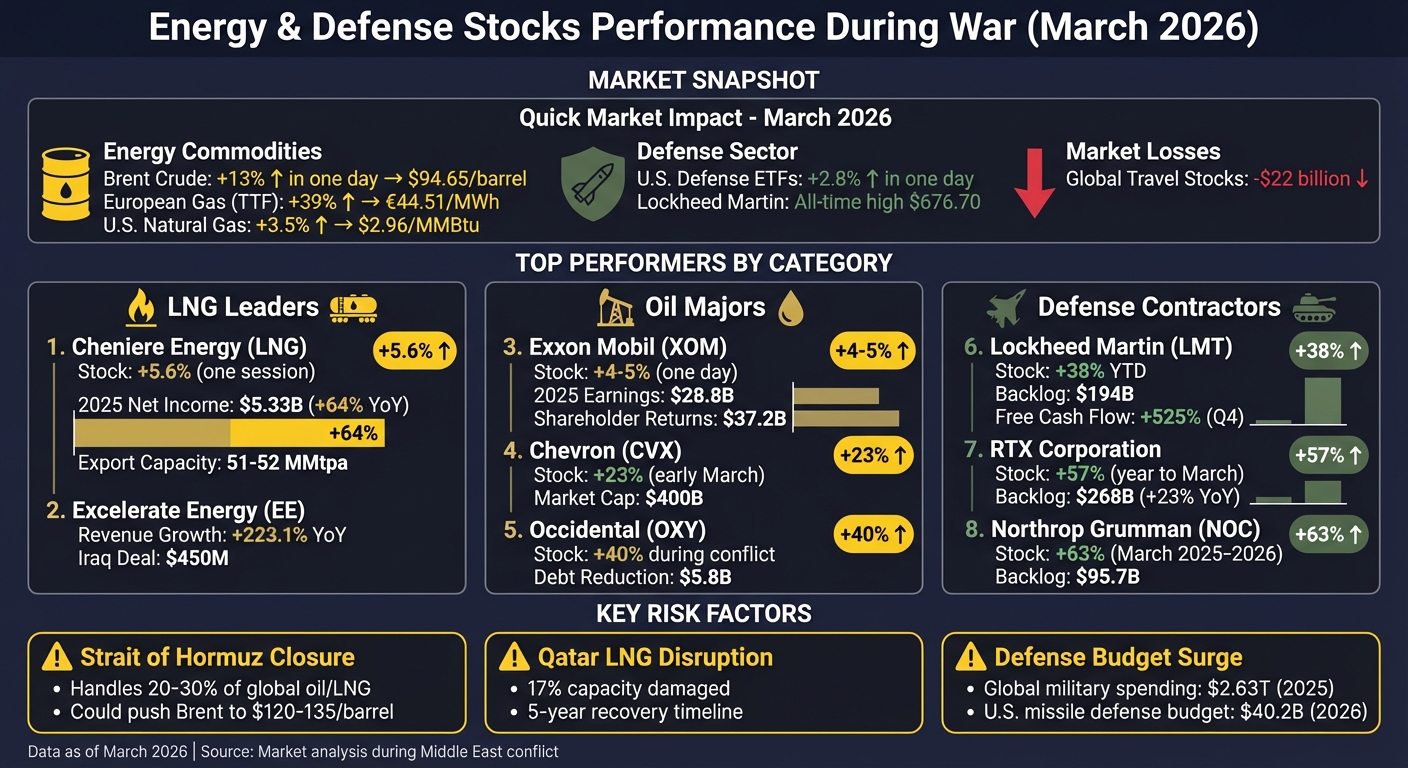
Energy and Defense Stocks Performance During March 2026 Middle East Conflict
1. LNG - Cheniere Energy - LNG Export / Natural Gas Infrastructure
Market Positioning During Geopolitical Conflicts
Cheniere Energy stands as a major player in the U.S. LNG market, controlling nearly 50% of the country’s export capacity. This key position links abundant American shale gas with energy-hungry global markets. For example, when Iranian attacks disrupted 17% of Qatar's LNG capacity, European gas prices spiked by 35%, leading to an urgent need for alternative suppliers. In response, Cheniere set a record in 2025 with 670 cargoes exported. The shift in European demand - from 34% of Cheniere’s exports in 2021 to 68% in 2025 - highlights the company’s strategic importance during such crises. This dominance allows Cheniere to thrive as commodity prices rise.
Exposure to Rising Commodity Prices
Cheniere benefits from a balanced revenue model, with about 90% of its volumes secured under long-term take-or-pay contracts and the remaining 10% exposed to spot market price fluctuations. This structure ensures stable cash flows while allowing the company to profit from price surges. For instance, in March 2026, as Euro-zone gas prices jumped 39% to €44.51 per megawatt-hour, Cheniere’s stock rose 5.6% in just one trading session.
The company’s financial performance reflects this strength. In 2025, Cheniere reported $5.33 billion in net income - a 64% increase from the prior year - on revenues that grew 27% to $19.98 billion. This growth was fueled by increased production and the completion of its Corpus Christi Stage 3 project. Jack Fusco, Cheniere’s President and CEO, summarized the year’s success:
"This commitment also enabled another record-setting year of LNG production in 2025, driving full year financial results to the high end of our guidance ranges".
Potential for Profit Growth Amid Supply Chain Disruptions
Cheniere’s integrated operations, covering everything from gas procurement to vessel chartering, provide a strong foundation to handle supply chain challenges effectively. The completion of the Corpus Christi Stage 3 project boosted exported volumes by 4%, with export capacity for 2026 expected to reach 51–52 million metric tonnes per annum. Looking ahead, the company forecasts adjusted EBITDA of $6.75–$7.25 billion for 2026 and has increased its share repurchase authorization to more than $10 billion through 2030. As of March 19, 2026, Cheniere’s stock was trading at $281.87, marking a 12.96% rise over the previous two weeks.
2. EE - Excelerate Energy - LNG Infrastructure (FSRU / Floating Terminals)
Market Positioning During Geopolitical Conflicts
Excelerate Energy operates one of the largest fleets of Floating Storage and Regasification Units (FSRUs), offering quick access to LNG without the need for permanent terminals. In October 2025, the company signed a $450 million deal with Iraq's Ministry of Electricity to establish the nation’s first floating LNG terminal at the Port of Khor Al Zubair. This project is a significant step for Iraq, as it reduces reliance on Iranian pipeline gas, which had already dropped from 50 million cubic meters per day to 25 million cubic meters per day earlier in 2025 due to sanctions and regional tensions. Steven Kobos, President and CEO of Excelerate Energy, highlighted the importance of this initiative:
"By combining terminal development, LNG supply, and operational expertise, we are helping Iraq secure reliable energy, diversify its fuel mix, and strengthen its long-term energy security".
FSRUs have a distinct advantage - they can be deployed within one to three years, far quicker than the four to six years required for traditional land-based terminals. Thomas Lersten, a senior official at the U.S. Department of State, also pointed out the broader geopolitical implications:
"This terminal opportunity demonstrates U.S. energy leadership and represents a vital step in advancing Iraq's energy security and reducing its reliance on Iranian pipeline gas".
This approach not only strengthens Excelerate's position in the market but also aligns with shifting energy dynamics during periods of geopolitical instability.
Exposure to Rising Commodity Prices
Excelerate Energy’s business model thrives on LNG price fluctuations. For example, the company reported a massive 223.1% year-over-year revenue increase, reaching $622.9 million in a single quarter. In March 2026, Iranian strikes disrupted Qatari LNG production, forcing India to cut industrial gas supplies by 30%. This situation underscored the high value of flexible infrastructure like FSRUs, which can quickly tap into alternative global supplies. Moreover, the Iraq project secures a minimum contracted offtake of 250 million standard cubic feet per day under a five-year agreement, while the FSRU Hull 3407 has the capacity to deliver up to 1,000 million standard cubic feet per day. These factors position Excelerate to reap substantial financial benefits even during turbulent times in the energy market.
Potential for Profit Growth Amid Supply Chain Disruptions
Excelerate’s integrated supply model ensures control over the entire LNG value chain, even during volatile market conditions. In March 2025, the company acquired New Fortress Energy’s Jamaica business for $1.055 billion, securing long-term contracts through 2039. Notably, 86% of this contracted revenue is protected under take-or-pay agreements. With global LNG demand projected to grow by 60% by 2040, Excelerate’s fleet of 10 operational FSRUs is well-positioned to meet the needs of nations striving for energy independence amid prolonged conflicts. This ability to adapt to changing circumstances solidifies Excelerate’s reputation as a leading energy infrastructure provider during uncertain times.
3. XOM - Exxon Mobil - Integrated Oil & Gas
Market Positioning During Geopolitical Conflicts
Exxon Mobil's integrated energy operations - from exploration to refining - provide a buffer against market swings, especially during periods of geopolitical tension. A notable example occurred in March 2026, during the U.S.-Iran conflict. Exxon Mobil's stock climbed 4–5% in a single day, opening between $160 and $161. This surge coincided with a 10–13% increase in Brent crude prices, which reached around $80 per barrel, spurred by attacks near the Strait of Hormuz.
Exxon’s significant upstream presence in stable regions like the Permian Basin and Guyana allows it to quickly respond to supply-driven price hikes. By late 2025, Exxon was producing 4.7 million barrels of oil equivalent per day - its highest annual output in over four decades - with a market value of over $635 billion as of March 2026. Analysts warn that a prolonged closure of the Strait of Hormuz, which handles about 20% of global oil supply (21 million barrels daily), could push Brent crude prices beyond $135 per barrel.
This strategic positioning not only secures stable earnings but also allows Exxon to benefit significantly from rising commodity prices.
Exposure to Rising Commodity Prices
Exxon’s integrated business model ensures resilience during periods of high commodity prices. Rising crude values drive upstream profits while also improving downstream margins. In the fourth quarter of 2025, Exxon reported $6.5 billion in profits on $82.3 billion in revenue, contributing to full-year earnings of $28.8 billion. That same year, Exxon returned $37.2 billion to shareholders, including $17.2 billion in dividends and $20 billion in stock buybacks.
The company is also expanding into natural gas through the Golden Pass LNG project, set to begin production in early 2026. This move comes as U.S. natural gas prices rose 3.5% to $2.96 per MMBtu due to regional supply shocks. As Reuters observed:
"Exxon Mobil, with vast upstream operations in the Permian Basin and Guyana, stands to benefit directly from elevated crude values".
Potential for Profit Growth Amid Supply Chain Disruptions

Run 24/7 while you sleep. Keep bots, platforms, and trade copiers online on a dedicated VPS.
Low-latency VPS hosting for your trading platform.
 CHINYC
 LON
From $29.99/mo


 CHI/CME futuresNYC/US marketsLON/FX EAs
 DUB/Polymarket
 AMS/EU FX
 FRA/Central EU
 TYO/APAC crypto
Exxon Mobil’s disciplined capital strategy and price resilience position it to capitalize on global supply chain disruptions. By prioritizing debt reduction and shareholder returns, the company has insulated itself from international supply challenges. With global oil consumption expected to rise by 640,000 barrels per day in 2026, Exxon’s production capabilities leave it well-placed to take advantage of this growth.
The International Energy Agency highlighted the scale of current disruptions, stating:
"The ongoing Middle East conflict has caused the largest-ever oil supply disruption in history, surpassing even the shocks experienced during the 1973 oil crisis and the 1990 Gulf War".
4. CVX - Chevron - Integrated Oil & Gas
Market Positioning During Geopolitical Conflicts
Chevron's operations in the Permian Basin give it a significant edge, insulating the company from instability in the Middle East. For example, after tensions in Iran escalated, Chevron's stock jumped 23% by early March 2026, as investors leaned toward its reliable domestic production. By that time, Chevron's market cap had soared to $400 billion, with shares climbing over 30% year-to-date.
One of Chevron's standout strengths lies in its end-to-end integration, which bolsters its stability in domestic markets. The company has also maintained a presence in Venezuela, working to restore production. Additionally, Chevron is exploring opportunities to acquire non-Russian assets from Lukoil, a U.S.-sanctioned entity, which could allow it to tap into high-quality infrastructure displaced by geopolitical conflicts. These strategic moves position Chevron to benefit from rising commodity prices amid global uncertainties.
Exposure to Rising Commodity Prices
Chevron has seen its profitability soar alongside Brent crude prices, which reached $85 per barrel in March 2026. Some analysts even predict that ongoing regional conflicts could push prices into triple digits. Between February 2022 and January 2026, Chevron joined four other global oil majors in generating $467 billion in combined profits, returning $444.4 billion to shareholders through dividends and stock buybacks. Dan Pickering, founder of Pickering Energy Partners, highlighted Chevron's advantage, stating:
"The U.S. is the biggest producer in the world, and our supplies are not bottlenecked. So [American producers'] financial results are absolutely going to benefit from this".
Chevron's refining operations also saw a boost during the conflict. The 3-2-1 crack spread - a measure of refining margins - jumped from $28.55 in late February 2026 to $44.33 by March 5, as fuel prices outpaced crude costs. This enabled Chevron to transfer higher costs to consumers while capturing additional margins.
Potential for Profit Growth Amid Supply Chain Disruptions
Chevron's strong market position and favorable pricing environment set the stage for significant profit growth. The company's strategic investments further enhance its ability to navigate supply chain challenges. For instance, its $53 billion acquisition of Hess, finalized in July 2025, is expected to contribute over 80% of its production growth through 2030. Chevron aims to reach a production rate of 4.2 million barrels of oil equivalent per day by 2030, up 13% from its 2025 projection of 3.7 million barrels per day. To address long-term inventory needs, Chevron has also committed to increasing its exploration budget by 50% through the end of the decade.
Industry analyst Chris MacDonald praised Chevron's approach, stating that it "is among the best players in the energy patch from a diversification and cash flow growth perspective" due to its ownership of "essentially the entire value creation lifecycle". This integrated structure ensures Chevron remains resilient, even when geopolitical disruptions or infrastructure challenges create stress within specific segments of the supply chain.
5. OXY - Occidental Petroleum - Oil & Gas Exploration & Production
Market Positioning During Geopolitical Conflicts
Occidental Petroleum (OXY) has strategically positioned itself to thrive during periods of geopolitical instability, especially when oil prices spike. A prime example of this was during the Iran conflict in March 2026. As a U.S.-based producer, OXY leveraged its domestic operations to capitalize on rising global oil prices caused by disruptions in the Middle East.
During the conflict, OXY's stock saw a 9% jump initially and ultimately climbed by 40%. Meanwhile, Brent crude prices surged nearly 70% in the same timeframe. Market analyst Itai Smidt highlighted the advantage of OXY's U.S. base:
"The United States is a net energy exporter, meaning domestic producers benefit from higher global prices without suffering the supply-chain disruptions hitting European and Asian competitors".
With an average resource breakeven of $38 per barrel and 84% of its portfolio profitable below $50 per barrel, OXY maintained strong margins, even as the "war premium" began to diminish.
Exposure to Rising Commodity Prices
OXY's low-cost production model ensures that it reaps substantial benefits when oil prices rise. For instance, when Brent crude jumped from under $80 to over $100 per barrel following military strikes in early 2026, OXY's efficient operations translated into significant profits. The company used this windfall to aggressively reduce its debt, cutting $5.8 billion in principal debt between mid-December 2025 and March 2026. This reduction brought its total debt down to approximately $15 billion, saving $365 million annually in interest expenses.
Despite the volatile market, OXY kept its 2026 capital budget between $5.5 billion and $5.9 billion, which was $550 million lower than the previous year. Additionally, the company increased its quarterly dividend by 8% to $0.26 per share in February 2026, effectively doubling its payout over the past four years. Matt DiLallo from The Motley Fool remarked:
"Occidental Petroleum wasn't expecting oil prices to surge this year... higher oil prices will enable Occidental Petroleum to produce an even bigger gusher of additional free cash flow this year".
Potential for Profit Growth Amid Supply Chain Disruptions
OXY's focus on the Permian Basin gives it a competitive edge, particularly during global supply chain disruptions. By concentrating on domestic production, the company avoids the shipping challenges that plague international competitors. In 2026, OXY aims to produce 1.45 million barrels of oil equivalent per day, with most of this output coming from U.S. operations. This domestic focus allows OXY to maintain steady production levels, even as European and Asian firms face tanker shortages and shipping route disruptions linked to the Strait of Hormuz closure.
Despite anticipating somewhat lower oil prices, OXY expects to generate over $1.2 billion in additional free cash flow in 2026 compared to 2025. Beyond traditional oil production, the company is diversifying its revenue streams with the STRATOS direct air capture project. This initiative ties revenue to carbon removal credits, reducing reliance on the unpredictable nature of commodity prices.
6. COP - ConocoPhillips - Upstream Oil & Gas Producer
Market Positioning During Geopolitical Conflicts
ConocoPhillips stands out as a safeguard against geopolitical instability, with 74% of its projected 2025 earnings tied to stable North American assets. These include the U.S. Lower 48, Alaska, and Canada, offering a stark contrast to competitors with significant exposure to more volatile regions like the Middle East. This focus on North America shields the company from potential disruptions stemming from geopolitical tensions elsewhere.
For instance, during the U.S.-Israeli strikes on Iran in March 2026, ConocoPhillips shares surged by 4.3% in just one day, coinciding with a 6.4% spike in WTI crude prices, which climbed above $71 per barrel. Billy Duberstein from The Motley Fool highlighted this advantage:
"ConocoPhillips is among the most exposed to the U.S. among large-cap oil stocks... its supply shouldn't be disrupted by the war".
This geographic strategy positions the company to capitalize on rising oil prices while minimizing risks tied to global conflicts.
Exposure to Rising Commodity Prices
As a company focused on upstream production, ConocoPhillips is particularly sensitive to fluctuations in oil prices. Producing approximately 2.33–2.36 million barrels of oil equivalent per day in early 2026, the company generated around $60.3 billion in revenue over the prior 12 months. Sergey Savastiouk, CEO of Tickeron, explained how price increases could benefit the company:
"For a large, low‑cost producer like ConocoPhillips, a sustained 10–20 dollar increase in benchmark prices would materially lift free cash flow".
With analysts predicting that Brent crude could hover between $90 and $100 per barrel if Middle Eastern supply issues persist, ConocoPhillips is well-positioned to see a significant boost in free cash flow from any price increases.
Potential for Profit Growth Amid Supply Chain Disruptions
ConocoPhillips continues to build on its solid earnings foundation, aiming for even greater profitability. The company's acquisition of Marathon Oil and progress on long-term projects like the Willow project in Alaska are expected to deliver over $1 billion in run-rate cost savings. Additionally, in 2025, the company achieved a 15% improvement in drilling and completion efficiency in the Lower 48, showcasing its operational strength.
With plans to return 45% of operating cash to shareholders in 2026 through dividends and buybacks, ConocoPhillips is taking advantage of the current high-price environment and geopolitical "war premium". Ryan Lance, Chairman and CEO, highlighted the company's strategic edge:
"Our best-in-class asset base remains a distinct competitive advantage, with the deepest and most capital-efficient Lower 48 inventory and a diverse, global portfolio of advantaged major projects and legacy assets".
7. EQT - EQT Corporation - Natural Gas Producer
Market Positioning During Geopolitical Conflicts
EQT Corporation, the largest natural gas producer in the U.S., has shown resilience during periods of geopolitical instability, particularly when conflicts in the Middle East disrupt global energy flows. For example, after Iranian drone attacks in March 2026, EQT's stock gained traction among investors. Unlike facilities in high-risk areas like Qatar's Ras Laffan or the Strait of Hormuz, EQT's North American operations remain unaffected by such disruptions. This domestic focus contributed to a 13% rise in EQT's stock between August 2025 and February 2026, bolstered by stronger natural gas prices and improved visibility into free cash flow. Natural gas, being less easily substituted and closely tied to industrial activity, allowed EQT's upstream cash flows to remain stable even during extended energy market shocks.
Exposure to Rising Commodity Prices
EQT's market strength extends to its ability to benefit from rising natural gas prices. In March 2026, natural gas benchmarks in the Euro-zone jumped 39% to €44.51 per megawatt-hour, while U.S. prices saw a smaller but notable increase of 3.5%, reaching $2.96 per MMBtu. With well costs per lateral foot dropping 13% year-over-year, these price increases translate directly into stronger free cash flow. For 2026, management has projected adjusted EBITDA of about $6.5 billion and free cash flow of roughly $3.5 billion. Analyst Nikko Henson highlighted this dynamic, stating:
"Lower structural costs allow incremental gas price strength to translate more directly into free cash flow, strengthening per-share value even without aggressive production growth".
This confidence is reflected in institutional investors holding approximately 91% of EQT's stock as of February 2026.
Potential for Profit Growth Amid Supply Chain Disruptions
EQT's strategic investments in infrastructure significantly enhance its ability to capture premium pricing and reduce market volatility. Projects like the Mountain Valley Pipeline and the Clarington Connector have opened access to high-demand regions, aligning with the growth of U.S. LNG exports as they fill supply gaps caused by Middle Eastern disruptions. In Q4 2025, EQT reported a 47% year-over-year revenue increase, reaching $2.39 billion. The company's average realized natural gas price rose 14.3% to $3.44 per thousand cubic feet equivalent during the same period. Analysts have set a target price of $74 per share, suggesting a 22% upside from its February 2026 price of $59. With a strong balance sheet - evidenced by a Net Debt/EBITDA ratio of 1.3x - EQT is well-positioned to seize emerging opportunities.
8. CHK - Chesapeake Energy - Natural Gas Producer
Market Positioning During Geopolitical Conflicts
Chesapeake Energy, now operating under the name Expand Energy after its merger with Southwestern Energy, stands as the largest natural gas producer in the U.S., with a production capacity of around 7 billion cubic feet per day. This scale makes the company a vital alternative to Middle Eastern energy sources, especially after missile attacks in March 2026 disrupted Qatari LNG infrastructure. Its shale reserves in the Marcellus and Haynesville basins are strategically located far from regions of conflict.
The company’s "Be LNG Ready" strategy represents a major shift from focusing solely on domestic sales to tapping into international markets. Management plans to allocate 15–20% of production volumes to international LNG pricing, allowing Chesapeake to bypass domestic market limitations and capture better margins globally. CEO Nick Dell'Osso highlighted the importance of this approach, stating:
"We don't see access to LNG as something that is a guaranteed arbitrage... We see it as a very important diversification strategy for our business".
This pivot to global LNG benchmarks underscores the company's efforts to strengthen its position in international markets while maintaining a strong domestic foothold.
Exposure to Rising Commodity Prices
Chesapeake’s profitability is closely tied to commodity price fluctuations. To reduce reliance on Henry Hub pricing, the company has embraced international benchmarks like the Japan Korea Marker (JKM). In 2024, Chesapeake secured a 15-year deal with Vitol to supply 1 million tonnes of LNG annually starting in 2028, indexed to JKM rather than domestic prices. This strategy paid off during the geopolitical disruptions of March 2026, enabling the company to benefit from a 35% surge in European gas prices.
Despite facing tough market conditions in 2023, Chesapeake achieved $2.4 billion in net income and returned approximately $840 million to shareholders through dividends and stock buybacks. The company’s operational flexibility - delaying completions during low-price periods and quickly activating its inventory of 75 drilled but uncompleted wells when prices rise - has proven to be a key advantage in navigating the volatility caused by geopolitical conflicts.
Potential for Profit Growth Amid Supply Chain Disruptions
Chesapeake has also managed to mitigate supply chain challenges by cutting capital and production costs by 4% and 8%, respectively, in 2024. Instead of maximizing output, the company focuses on maintaining strategic production capacity, building an inventory of short-cycle projects that can be deployed quickly when global demand spikes. Ben Marshall, Head of Vitol Americas, emphasized the evolving energy dynamics:
"The global energy landscape has changed significantly in the last two years, which has highlighted the importance of U.S. natural gas production and liquefaction in satisfying the world's energy needs".
With U.S. natural gas production expected to grow from 100 Bcf/d to 120 Bcf/d by the next decade, Chesapeake is well-positioned to capitalize on this expansion. The company’s first binding LNG export deal with the Delfin floating LNG project (0.5 mmty) marks the beginning of its international growth, solidifying its role as a major player in the global energy market during a time of heightened geopolitical tensions.
9. SHEL - Shell plc - Global Integrated Energy (Brent Exposure)
Market Positioning During Geopolitical Conflicts
Shell stands out as a key player during periods of geopolitical instability, offering direct exposure to rising oil prices. As a global energy giant, it benefits from a "quality bias", attracting investors seeking stability in volatile markets. For example, in March 2026, military actions in the Middle East caused Brent crude prices to spike 8.8%, reaching $79.25 per barrel. In response, Shell's share price climbed 3.7%. This close link to oil benchmarks is significant, especially considering that 20% to 30% of the world's oil and LNG supply passes through the Strait of Hormuz.
Shell’s diversified operations outside conflict-prone areas give it a strategic edge. James Hosie, an analyst at Shore Capital, highlighted this advantage:
"Higher near-term oil prices should continue to support the share prices of oil and gas producers operating outside the region and is a fresh reminder of the value of domestic energy security".
The company’s North Sea operations and its extensive global trading network allow it to fill supply gaps when disruptions occur in the Middle East. This operational diversity underpins Shell’s strong performance during uncertain times.
Exposure to Rising Commodity Prices
Shell’s integrated business model thrives as commodity prices increase. A $10 rise in Brent crude boosts its free cash flow yield by approximately two percentage points. Additionally, upstream production, which contributes 60% to 70% of earnings, experiences a 40% margin increase for every 13% rise in oil prices. This was evident in early March 2026, when UK natural gas prices surged by 25% to 98.5p per therm, reflecting Shell’s significant market presence.
In 2025, Shell generated $42.9 billion in cash flow from operations and began a $3.5 billion share buyback program in Q1 2026. The company’s focus on LNG expansion - aiming for 4% to 5% annual sales growth through 2030 - positions it well to benefit from rising regional benchmarks. For instance, European natural gas prices soared by 39% to €44.51 per megawatt-hour in March 2026, further enhancing Shell’s free cash flow.
Potential for Profit Growth Amid Supply Chain Disruptions
Shell’s integrated structure provides a buffer against supply chain disruptions. Since 2022, the company has achieved $5.1 billion in cost savings, surpassing its 2028 efficiency targets. Its agile trading operations also capitalize on regional price imbalances. With a gearing ratio of 20.7% and net debt at $45.7 billion, Shell remains financially flexible during periods of market instability.
Building on this solid foundation, Shell maintains a defensive stance in volatile markets. Devin McDermott, an analyst at Morgan Stanley, underscored this approach:
"We recommend sticking with what's working - remain defensive with a quality bias amid this period of heightened volatility".
Analysts predict that Brent crude could hit $120 per barrel if disruptions in the Strait of Hormuz persist for more than three weeks. Such a scenario would significantly boost upstream margins. Historically, regime changes in oil-producing nations have led to oil prices remaining 30% higher for at least three months, creating sustained profit opportunities for globally diversified companies like Shell.
10. BP - BP plc - Global Oil & Gas (Brent Exposure)
Market Positioning During Geopolitical Conflicts
BP's reliance on Brent crude has proven advantageous during times of geopolitical tension. For example, in early March 2026, Iran's blockade of the Strait of Hormuz - responsible for 20% of the world's oil supply - pushed Brent crude prices to a one-year high of $80 per barrel. This surge translated to a significant boost for BP, whose stock climbed 16% year-to-date by March 3, followed by an additional 9.6% rise over the next month. In contrast, competitors like ExxonMobil saw only a modest 0.9% gain during the same period.
Under CEO Murray Auchincloss, BP has shifted its strategy to capitalize on these market dynamics. Pressured by Elliott Management, which acquired a 5.006% stake in 2025, BP abandoned its ambitious renewable energy expansion plans in February 2026. Instead, the company redirected its focus to seven major upstream projects launched in 2025, designed to maximize cash flow when Brent prices exceed $70 per barrel. Financial writer Michael Abadha summed up the situation:
"The closure of the Strait of Hormuz has pushed Brent crude to $80, which is directly increasing BP's profit margins and attracting investors who want a safe investment during this conflict".
Exposure to Rising Commodity Prices
BP's performance is closely tied to Brent crude prices, the benchmark for its global upstream operations and trading activities. JPMorgan analysts have suggested that a prolonged closure of the Strait of Hormuz could push Brent prices to between $120 and $130 per barrel. With BP currently trading at a forward P/E ratio of under 9x, this scenario could present a significant opportunity for growth in a high-price environment.
The company's integrated business model - covering upstream production, refining, and a sophisticated trading division - positions it to benefit from tighter fuel markets during supply disruptions. By the end of 2025, BP had reduced its net debt to $22.2 billion and achieved a 14% Return on Average Capital Employed. Additionally, its dividend yield exceeds 5%, supported by a policy targeting 4% annual growth. Zacks Equity Research highlighted this advantage:
"BP's upstream activities have substantial exposure to rising oil prices and are expected to support higher profits and cash flows".
Potential for Profit Growth Amid Supply Chain Disruptions
In February 2026, CEO Murray Auchincloss paused BP's share buyback program to prioritize debt reduction and a $20 billion asset divestiture plan. As CFO Kate Thomson noted, net debt was expected to rise temporarily before declining later in the year. This move is part of BP's effort to streamline its portfolio toward high-margin assets while maintaining flexibility.
BP's operational strength adds to its stability during supply chain challenges. In 2025, the company reported 96.1% upstream plant reliability and 96.3% refining availability. Its robust trading desk and refining capabilities allow BP to capitalize on regional price imbalances caused by shipping disruptions. However, a swift resolution to the conflict could remove the "war premium" on oil prices, potentially leading to a stock correction. This strategic approach underscores BP's ability to adapt to volatile market conditions, setting the stage for further insights into global energy players in the next section.
11. TTE - TotalEnergies - Global Energy / LNG & Oil
Market Positioning During Geopolitical Conflicts
TotalEnergies stands out among Western energy companies due to its significant presence in the Middle East, where 29% of its production is based. This includes key operations in the United Arab Emirates and a strategic partnership with QatarEnergy, the state-owned company responsible for about 20% of the global LNG supply.
The U.S.-Israel-Iran conflict in March 2026 posed a major challenge for the French energy firm. Iranian drone strikes disrupted 17% of Qatar's LNG production capacity, with recovery expected to take up to five years, directly impacting TotalEnergies' projects in the region. This supply disruption caused European natural gas benchmarks to spike by 40%, reaching €44.51 per megawatt-hour, while Brent crude futures rose 7% to $77.74 per barrel. Reuters summarized the situation well:
"Even as the war threatens some production, it has caused a surge in oil and gas prices that could help prop up the companies' profits".
These geopolitical tensions highlight the volatility of energy markets and the delicate balance companies like TotalEnergies must navigate.
Commodity Price Exposure
TotalEnergies' wide-ranging global portfolio positions it to capitalize on rising energy prices, even in the face of regional instability. The closure of the Strait of Hormuz forced the company to rely on alternative supply chains and take advantage of higher spot prices. Its operations span upstream, refining, and LNG markets, allowing it to benefit from regional price differences.
With 29% of its production tied to the Middle East, TotalEnergies faces more exposure to regional risks than competitors like Exxon Mobil and Shell, which each have 20% of their output in the region. This concentrated presence creates a distinct risk-reward scenario for the company. As TradingKey noted:
Stay online and closer to execution. Choose a VPS location for CME futures, New York markets, London FX, API trading, and more.
Host your platform near the market route that matters.
CHINYCLONFrom $29.99/mo
CHI/CME futuresNYC/US marketsLON/FX EAsDUB/PolymarketAMS/EU FXFRA/Central EUTYO/APAC crypto"In a landscape ruled by uncertainty, [energy stocks] have become the market's few reliable hedges against geopolitical risk".
This dynamic underscores the potential for profit gains, even amid supply chain challenges.
Profit Growth Prospects
TotalEnergies faces a balancing act between operational risks and financial opportunities. While disruptions in crude and LNG transit through the Strait of Hormuz pose challenges, the resulting price spikes could help mitigate losses from reduced volumes. Elevated spot prices, driven by scarcity, have the potential to generate significant profits, offsetting the impact of facility shutdowns. The company's financial performance will largely depend on how long these disruptions persist and whether commodity prices remain elevated during that time.
12. EPD - Enterprise Products Partners - Midstream / Pipelines & NGLs
Market positioning during geopolitical conflicts
Enterprise Products Partners is one of the largest and most diversified midstream operators in the U.S., with an extensive network including pipelines, natural gas processing, NGL fractionation, storage, marine terminals, and export infrastructure. This creates a different risk profile than exploration and production companies because EPD focuses on moving and processing hydrocarbons rather than producing them.
Why does midstream infrastructure matter when conflicts disrupt supply?
When countries conflict, this positioning becomes particularly valuable. Supply disruptions increase the importance of U.S. infrastructure that can move hydrocarbons between production regions, storage facilities, refineries, and export terminals. EPD's scale and integration across those links enable it to participate in changing energy flows without requiring oil prices to remain permanently elevated.
How did EPD's results demonstrate the resilience of this model?
The company's 2025 results validate this model. Enterprise generated record adjusted cash flow from operations of $8.7 billion, while pipeline transportation volumes increased to 13.7 million barrels per day from 13.0 million in 2024. It raised its distribution for the 27th consecutive year. (Enterprise Products Partners L.P.)
Exposure to Rising Commodity Prices
EPD is less directly exposed to crude and natural-gas prices than upstream producers such as Devon or Antero. Much of its business generates fee-based revenue from transporting, processing, and storing hydrocarbons, so a geopolitically driven commodity-price spike does not automatically translate to a one-for-one increase in EPD's earnings.
However, higher prices can benefit the partnership indirectly by encouraging producers to maintain or increase drilling activity and by increasing demand for transportation, processing, storage, and export capacity. EPD's exposure to NGLs and natural gas provides leverage to shifts in U.S. production and global demand.
Why is EPD better described as an infrastructure play than an oil-price trade?
This makes EPD more of an infrastructure play on sustained energy flows than a pure oil-price trade. Its 2025 results showed natural-gas processing inlet volumes, NGL fractionation volumes, and pipeline transportation volumes all reaching higher levels, while the partnership retained $3.2 billion of distributable cash flow for reinvestment. (Enterprise Products Partners L.P.)
Potential for Profit Growth Amid Supply Chain Disruptions
Supply disruptions could increase the strategic value of EPD's infrastructure if producers, refiners, and exporters need alternative routes to move hydrocarbons. The partnership's large transportation and processing footprint enables it to capture additional volumes without depending on a single commodity or geographic basin.
EPD expects $1.9 billion to $2.3 billion of organic growth capital investment in 2026, alongside approximately $580 million of sustaining capital expenditures. (Enterprise Products Partners L.P.)
This makes EPD valuable during prolonged disruptions rather than short-lived price spikes. The company profits when energy moves through infrastructure where capacity, processing, and export access become increasingly valuable, not when oil prices spike dramatically.
13. ET - Energy Transfer - Midstream / Natural Gas & LNG Infrastructure
Market Positioning During Geopolitical Conflicts
Energy Transfer is a major U.S. midstream operator with extensive natural-gas infrastructure spanning natural gas, crude oil, NGLs, and refined products. This service diversity matters during geopolitical conflicts because disruptions rarely affect every commodity and transportation route equally. For example, a crude-export disruption can simultaneously increase demand for alternative natural-gas supplies, LNG infrastructure or domestic transportation capacity.
Why does domestic demand make Energy Transfer's infrastructure more resilient?
Energy Transfer's natural gas infrastructure could become especially important as the U.S. responds to growing electricity demand from data centers and other power-intensive industries. The company has expanded connections to power-generation and data-center projects, creating a domestic demand driver less dependent on conventional oil-market cycles.
Exposure to Rising Commodity Prices
ET is primarily a midstream toll-road business, not a pure bet on oil or gas prices. When commodity prices rise, activity and volumes across the system improve. The biggest benefit occurs when higher demand encourages producers and end users to move more hydrocarbons through ET's infrastructure.
Why does natural gas play a central role?
Natural gas is especially important. Worldwide demand for liquefied natural gas (LNG) and rising U.S. electricity consumption create greater need for systems that gather, process, and transport gas. At the same time, international tensions make reliable U.S. gas supplies more valuable.
What makes ET's position a middle-ground opportunity?
This gives ET a potentially attractive middle ground: it can participate in a stronger energy market without carrying the same direct commodity-price exposure as an E&P company.
Potential for Profit Growth Amid Supply Chain Disruptions
Problems between countries could increase demand for U.S. natural gas and LNG infrastructure as international buyers seek reliable alternatives to disrupted supply. ET's extensive transportation network positions it to capture that additional demand.
Data-center development and new power generation are creating increased demand for natural-gas infrastructure, giving ET a second growth engine alongside traditional energy consumption.
The longer-term opportunity comes from the infrastructure required to deliver reliable gas to LNG facilities, power plants, and rapidly expanding electricity loads.
14. MPLX - MPLX - Midstream / Crude, Products & Natural Gas
Market Positioning During Geopolitical Conflicts
MPLX is a diversified midstream partnership with operations spanning crude oil and products logistics, natural gas, and NGL services. Its infrastructure includes pipelines, gathering systems, processing facilities, fractionation facilities, storage assets, and marine transportation.
This range of services provides a defensive position during geopolitical conflicts. Rather than depending on commodity prices, MPLX benefits when producers and refiners need transportation, storage, and processing capacity, whether oil prices rise or fall.
Its connection to Marathon Petroleum adds strategic exposure to a large U.S. refining and logistics network, positioning the business around the physical movement of energy rather than directional crude prices.
Exposure to Rising Commodity Prices
MPLX has less direct commodity-price exposure than exploration and production companies. Rising oil and gas prices encourage drilling and production activity, increasing material flow through MPLX's gathering, transportation, and processing assets. This makes MPLX particularly attractive during geopolitical disruptions that spur additional production and boost infrastructure utilization.
MPLX does not need oil prices to keep rising forever. Its investment case rests on volume growth, infrastructure utilization, and cash-flow durability rather than correctly predicting crude-price movements.
Potential for Profit Growth Amid Supply Chain Disruptions
Cross-border issues create traffic jams across the energy system, increasing the need for infrastructure that moves crude oil, refined products, natural gas, and NGLs between regions.
MPLX's varied asset collection positions it to capture those flows. The partnership's 2025 annual report emphasizes operational efficiency, prudent investment decisions, and sustained investor returns, grounding its investment case in steady infrastructure economics rather than geopolitical catalysts alone. (MPLX.com)
This makes MPLX attractive for investors seeking energy-sector disruption exposure without the earnings volatility of upstream producers. Profit growth stems from moving more hydrocarbons through the system as supply chains become more valuable.
15. KRP - Kimbell Royalty Partners - Oil & Gas Royalties
Market Positioning During Geopolitical Conflicts
Kimbell Royalty Partners owns mineral and royalty interests rather than transporting or processing hydrocarbons. Its interests span more than 17 million gross acres across major U.S. producing regions, including the Permian, Eagle Ford, Bakken, and other resource plays. (Kimbell Royalty Partners) This structure provides broad exposure to U.S. oil and gas production without the costs of drilling and completion operations.
During geopolitical conflicts, this model becomes attractive because Kimbell participates in production economics while avoiding the capital burden E&P companies carry. If higher prices encourage producers to increase drilling on Kimbell's acreage, the partnership benefits from both higher commodity prices and increased production volumes.
Exposure to Rising Commodity Prices
Kimbell is more directly exposed to commodity prices than EPD, ET, or MPLX. Royalty revenue is linked to the production and realized prices of underlying oil and natural gas assets, creating meaningful upside when geopolitical tensions push crude or natural gas prices higher. Unlike a midstream toll-road operator, Kimbell sees direct revenue improvement when hydrocarbon values increase.
The trade-off is equally important. If prices fall sharply, royalty revenue declines, and weaker commodity economics can cause producers to reduce drilling activity. Kimbell therefore offers more commodity upside than midstream names but carries greater direct exposure to price reversals.
Potential for Profit Growth Amid Supply Chain Disruptions
Supply disruptions can create a favorable setup for Kimbell if they push commodity prices higher without materially reducing production from the properties underlying its royalty portfolio.
The company benefits from its broad geographic footprint. Kimbell reports that nearly 96% of its production comes from seven premier U.S. onshore resource plays, while its interests span approximately 135,000 gross wells. (Kimbell Royalty Partners) This diversification reduces dependence on any single basin or producer, positioning Kimbell to capture profit growth from higher commodity prices, continued drilling activity, and production growth across its large royalty portfolio.
16. AR - Antero Resources - Natural Gas & NGLs
Market Positioning During Geopolitical Conflicts
Antero Resources focuses on natural gas and natural gas liquids, with operations concentrated in the Marcellus Shale in Appalachia.
This position makes Antero particularly important when world tensions affect global gas markets, as U.S. natural gas becomes more valuable when international buyers need extra LNG supplies. NGL demand also provides another growth avenue for earnings.
Antero's 2026 position changed significantly after it acquired HG Energy, which added about 385,000 net acres in the center of the Marcellus Shale and expanded Antero's footprint in Appalachia. (Antero Resources Corporation)
How does exposure to rising commodity prices affect Antero's revenue?
Antero has significant direct exposure to natural-gas and NGL prices, so geopolitical-driven energy price increases flow more directly into its revenue and cash-flow outlook than they would for a fee-based midstream operator. Its NGL exposure is particularly relevant because ethane, propane, and butane benefit from strong petrochemical and international demand. Antero's access to Gulf Coast markets provides a pathway for its natural gas and NGL production to participate in broader U.S. and international demand.
Do infrastructure constraints limit the upside from higher commodity prices?
However, Appalachian producers face infrastructure constraints and transportation costs. Rising commodity prices don't automatically translate into maximum margins if takeaway costs or regional basis differentials remain unfavorable.
What drives Antero's profit growth potential amid supply chain disruptions?
Antero's biggest opportunity during an energy-supply disruption is the combination of rising commodity prices and increasing demand for U.S. natural gas and NGLs.
How is Antero managing downside risk while investing in production?
The company is managing downside risk by adding natural-gas swaps and basis hedges for 2026 and 2027, including positions acquired through the HG Energy transaction. (Antero Resources Corporation) For 2026, Antero expects capital expenditures of $1.1 billion to $1.3 billion and plans to complete 70 to 80 net horizontal wells in the Appalachian Basin. (Antero Resources Corporation)
What limitations cap Antero's realized price upside?
This creates a potentially powerful earnings setup if gas and NGL prices remain elevated: Antero has expanded its resource base, is investing in additional production, and has hedges to reduce commodity-price downside. The biggest limitation remains Appalachia's infrastructure and transportation constraints, which prevent higher headline commodity prices from translating fully into realized prices.
17. DVN - Devon Energy - U.S. Oil & Gas / Shale
Market Positioning During Geopolitical Conflicts
Devon Energy is one of the more direct beneficiaries of a geopolitical energy shock because it is an upstream producer, not an infrastructure operator. Its portfolio now has significantly greater scale following the completion of its merger with Coterra Energy in May 2026.
The combined company has a leading position in the Delaware Basin alongside exposure to several other major U.S. shale regions. Devon expects the enlarged platform to generate $1 billion in annual pretax collaboration on a run-rate basis by the end of 2027. (Devon Energy Investors)
That scale matters during geopolitical conflicts because disruptions to global supply can raise the value of incremental U.S. oil and gas production. Devon therefore has greater upside from commodity-price spikes than the midstream companies on this list, though it also carries greater commodity-price risk.
Exposure to Rising Commodity Prices
Devon's earnings are directly tied to oil, natural gas, and NGL prices. Geopolitical disruptions that push crude prices higher hit revenue and free cash flow more immediately than they would for fee-based pipeline companies.
The company's Permian Basin exposure is substantial, with more than 60% of its approximately $4.9 billion 2026 capital program targeting the region. Total 2026 production is expected to be about 1.38 million barrels of oil equivalent per day, including 500,000 barrels per day of oil. (Devon Energy)
This concentration gives Devon significant operating leverage to higher oil prices, but falling prices create the opposite effect, making Devon inherently more cyclical than EPD, ET, or MPLX.
Potential for Profit Growth Amid Supply Chain Disruptions
A long-term geopolitical disruption could create one of the clearest profit-growth opportunities for Devon among these companies. If global supply falls while demand remains strong, higher oil and gas prices can increase the value of Devon's production without requiring proportional increases in capital spending.
The larger Devon has potential to capture operating efficiencies from the Coterra combination. Management expects $600 million of synergies in 2027 and remains on track toward $1 billion of annual pretax collaboration by year-end 2027. (Devon Energy) Devon targets returning up to 70% of free cash flow to shareholders through its dividend and share-repurchase program. (Devon Energy)
This makes Devon one of the more aggressive geopolitical-energy plays in the group. Unlike midstream names, it can benefit substantially from direct commodity-price shocks, but investors must accept that the same mechanism works against the company if oil and gas prices drop once supply disruptions ease.
How QuantVPS Supports Energy and Defense Stock Trading
Energy and defense stocks often see dramatic price swings during geopolitical crises. For instance, disruptions in the Strait of Hormuz have previously caused Brent crude prices to spike nearly 40% and European gas prices to jump 60% in short timeframes. In such volatile moments, milliseconds can make all the difference. QuantVPS provides ultra-low latency connections - down to just 1 millisecond - to major exchanges, a stark contrast to the 50–100 millisecond latency typical of standard home internet setups. Research highlights the importance of speed, with findings showing that reducing execution latency by even 1 millisecond can boost high-frequency trading (HFT) strategy returns by 5% to 15% annually. As fintech entrepreneur Ace Zhuo explains:
"The difference between success and failure in HFT isn't strategy complexity or market knowledge – it's whether your orders reach the exchange 0.5 milliseconds before the next trader's".
This speed advantage is essential for traders aiming to capitalize on the rapid fluctuations in energy and defense markets.
QuantVPS pairs this speed with flexible pricing options to suit different trading needs. The platform offers eight pricing tiers, starting with the VPS Lite plan at $41.99 per month (billed annually). This plan includes 4 cores, 8GB RAM, and 70GB NVMe storage, making it ideal for traders managing 1–2 charts. For those handling 5–7 charts, the VPS Ultra plan costs $132.99 per month (annual billing) and provides 24 cores, 64GB RAM, and 500GB NVMe storage. Institutional traders managing 7+ charts can choose the Dedicated Server plan for $209.99 per month (billed annually), which delivers 16+ dedicated cores, 128GB RAM, and over 2TB of NVMe storage. Annual billing offers savings of up to 36% compared to monthly payments, and all plans come with a 14–30 day money-back guarantee for a risk-free trial.
Reliability is another cornerstone of QuantVPS, with the platform guaranteeing 99.95% to 99.99% uptime. This ensures that automated trading strategies remain operational, even if personal devices go offline. Servers are strategically placed in financial hubs like Chicago, New York, and London to reduce slippage during high-volatility events. The platform supports popular trading software such as NinjaTrader, MetaTrader, and TradeStation, and includes robust security measures like DDoS protection, data encryption, and intrusion detection systems to protect sensitive trading data. Professional plans also feature real-time CPU and RAM monitoring tools, helping traders avoid system crashes during sudden market surges. These features work together to ensure that traders maintain a competitive edge, even in the most unpredictable markets.
Conclusion
Energy and defense stocks have proven to be reliable hedges against geopolitical risk during the ongoing Middle East conflict, which began impacting markets on February 28, 2026. While broader indices like the S&P 500 have experienced sell-offs during such crises, these sectors have shown resilience and, in some cases, notable gains. For example, Brent crude prices have climbed nearly 40%, and European TTF gas prices have soared by almost 60%. Meanwhile, defense contractors like Lockheed Martin reached an all-time high of $676.70 in mid-March. Georgina Lu of TradingKey encapsulated this trend:
"In a landscape ruled by uncertainty, [defense and energy] have become the market's few reliable hedges against geopolitical risk".
These movements are not just based on market sentiment but reflect real supply chain disruptions. When transit volumes decline sharply, markets shift from speculative pricing to being driven by actual physical scarcity. Defense stocks, in particular, are benefiting from surging demand for precision-guided munitions and missile systems. This dynamic highlights how physical shortages are now dictating market behavior.
Success in these volatile conditions depends on distinguishing between short-term opportunities and longer-term defensive strategies. For instance, tanker stocks exposed to spot markets can generate quick profits from rising freight rates, while missile-defense suppliers stand to benefit from sustained growth as NATO nations expand defense budgets through 2026. Key chokepoints like the Strait of Hormuz remain critical; disruptions in these areas can quickly shift pricing dynamics from sentiment to scarcity.
The broader economic picture is also shifting. As noted in our analysis of LNG and integrated oil stocks, the narrative has moved from expectations of a "soft landing" to concerns over "energy-led stagflation." Commodity price shocks are now rippling through labor markets and inflation indices. This environment tends to favor U.S.-based energy producers, who are less vulnerable to gas-price shocks than energy-importing industries in Europe and Asia. For traders managing positions across these sectors, maintaining operational efficiency and executing trades quickly is vital. In a volatile market, a matter of milliseconds can determine whether you capitalize on a price spike or miss out entirely.
Staying ahead requires monitoring vessel transits, Flash PMIs, and defense procurement cycles. Whether you're tracking LNG infrastructure plays like Cheniere Energy or observing defense modernization efforts through companies like Northrop Grumman, combining strong market insights with dependable trading tools ensures you're ready to act when volatility strikes and seize emerging opportunities.
FAQs
Why do energy and defense stocks often rise during wars?
During times of war, energy and defense stocks tend to perform well, driven by heightened demand for their offerings. For instance, defense giants like Lockheed Martin often see increased business as governments ramp up spending on military equipment and advanced systems.
At the same time, energy stocks - especially those tied to oil, natural gas, and LNG - typically benefit from surging energy prices. Geopolitical tensions and fears over supply disruptions push these prices higher, making these stocks attractive to investors. Both sectors are often viewed as safe-haven investments during periods of conflict.
Which matters more for these stocks: higher commodity prices or supply disruptions?
Higher commodity prices play a crucial role for these stocks because they thrive on rising oil, natural gas, and energy infrastructure prices. While supply disruptions and geopolitical tensions can intensify these trends, the core factor remains the upward movement in commodity prices.
What are the biggest risks if the conflict de-escalates quickly?
If tensions ease rapidly, one of the main risks would be a steep decline in energy prices. This could hurt energy stocks and industries connected to them. Similarly, reduced defense and military spending could put pressure on defense-related stocks.